Retire With SwanRetire Blessed Income Blueprint Fundamentals / Life before math
Selected pages for Jordan & Taylor · An invented household
An ordinary Tuesday. A different kind of paycheck.
Jordan, 64, plans to leave full-time work on October 1. Taylor, 66, is already retired. Their home is paid for. They picture long breakfasts, afternoons with family, and time to manage their own investments.
Fictional household, priorities, and illustration. This is a selection from a Blueprint, not the complete deliverable.
Retire With SwanRetire Blessed Income Blueprint Financials / The starting picture
Monthly spending · $8,000
Give the money a job before it moves.
Pension, after withholding
$3,000
The gap savings must fill
+ $5,000
Monthly household spending
$8,000
Spending includes healthcare, travel, and annual bills. Income taxes beyond pension withholding are separate. No Social Security income is assumed in this 12-month example.
Bank cash, assigned by purpose$90,000 total
Paycheck cash$30,000
The source of the first monthly transfers.
Emergency reserve$30,000
Kept outside the paycheck route.
Tax provision*$30,000
Also kept separate from spending cash.
The later paychecks have dates.
Separate Treasury bills in their taxable brokerage account are assumed to return $15,000 of principal in December, March, and June, before the next quarter begins.
*The tax provision is an invented earmark, not a tax estimate. Interest is excluded from the maturity figures. Other assets and the full balance sheet are outside these excerpts.
Retire With SwanRetire Blessed Income Blueprint A / Asset Growth & Income
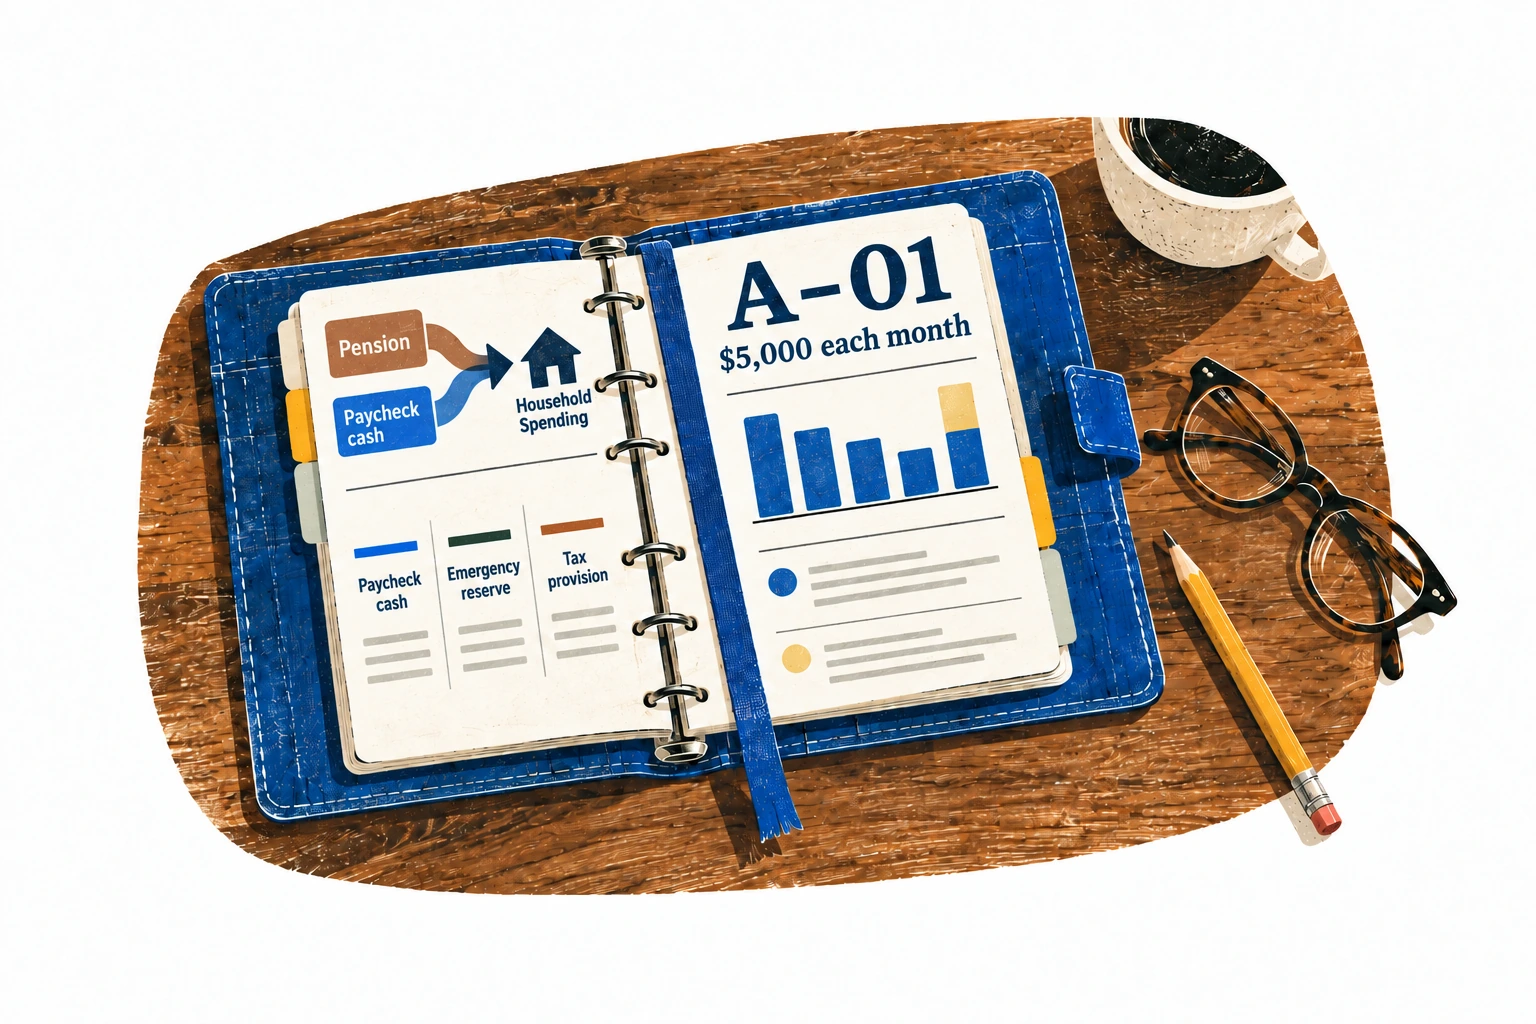
Household rule A–01
The paycheck has an address and a date.
Move $5,000 from designated paycheck cash to checking on the first business day of each month, beginning in October.
FIRST QUARTER / PAYCHECK CASH REMAINING
Starting paycheck cash
$30,000
After October transfer
$25,000
After November transfer
$20,000
After December transfer
$15,000
After December’s $15,000 principal refill
$30,000
The December maturity refills what the first three paychecks used. Interest is excluded. This is a cash schedule, not an investment-performance projection.
Why this rule fits here
The assigned cash funds the first quarter without an investment sale or a new IRA distribution. Emergency and tax cash keep their separate jobs.
This arithmetic does not establish lifetime sustainability. Setup and the conditions for revisiting the rule are on page 4.
Retire With SwanRetire Blessed Income Blueprint A / Putting rule A–01 to work
One person responsible. A clear definition of done.
Put the paycheck in motion.
Before October 1Owner: Jordan
Set up the first three transfers.
Schedule the monthly $5,000 transfers. Taylor checks the instructions and knows where to find them.
Done when the first deposit arrives and both can find the schedule.
By November 1Or cash at $20,000 or less
Confirm the next refill.
Jordan confirms the next $15,000 maturity with the provider. Refill paycheck cash in December, March, and June. Continue the $5,000 monthly transfers through September.
Done when the maturity is confirmed and, at each refill, the principal reaches paycheck cash.
When to reopen the rule
If income, spending, or a maturity changes, Jordan requests revised advice. A delayed maturity does not authorize spending the emergency or tax reserves.
Income changesSpending changesMaturity changes
The household carries out these steps with its providers. This sample does not include ongoing monitoring or transaction authority.
Retire With SwanRetire Blessed Income Blueprint C / Comprehensive Tax Planning
The reasoning beside the rule
The account matters.
The first quarter needs $15,000 from savings. The account changes the arithmetic.
Designated bank cash
Taken from the account
$15,000
Tax on cash principal
$0
Available to spend
$15,000
Fully pre-tax IRA
Taken from the account
$18,750
Assumed tax
− $3,750
Available to spend
$15,000
Illustration only: a 20% tax assumption on the IRA distribution gives $15,000 ÷ 80% = $18,750. The rate is invented; it is not a tax bracket or household tax estimate.
What this tells us
Existing cash funds the first quarter without adding IRA income. It still reduces household assets. This is a near-term cash choice, not a finding about the lowest lifetime tax.
“Then should we convert some to Roth?”
A complete tax analysis would compare no conversion with specific amounts, current tax, future withdrawals, and possible Medicare effects. This excerpt recommends no conversion amount. Roth withdrawals are also an option to evaluate.
Retire With SwanRetire Blessed Income Blueprint The 12-Month Crossing Plan
October 2026–September 2027
The next year, in view.
The Blueprint is adopted in this fictional scenario. These selected actions are planned, not completed.
Oct–DecBEGIN
Put the paycheck to work.
Jordan: set up A–01 and confirm the December maturity. Instructions and timing: pages 3–4.
Taylor: before any conversion, coordinate records with the planner and tax preparer.
Done: first deposit received; maturity confirmed; any conversion amount, tax funding, and authorization documented. Zero remains an option.
Jan–MarFOLLOW THROUGH
Keep the records with the decisions.
Taylor: send actual pension, withdrawal, and conversion records to the tax preparer. Jordan: verify the March maturity and direct the $15,000 principal to paycheck cash.
Done: records received, filing and payment deadlines confirmed, and refill received.
Apr–JunCOMPARE
Let real life inform the next decision.
Jordan: compare three months of actual spending; note insurance changes; verify the June refill.
Done: cash and spending reconciled; changed assumptions referred for advice.
Jul–SepPREPARE
Leave a clear handoff.
Taylor: update income choices, contacts, and beneficiaries. Decide whether to engage advice for next year.
Done: both can find the plan and professional contacts.
A visible year. A named person. Evidence that the step is complete.
Retire With SwanRetire Blessed Income Blueprint Continuity / A plan you can use
The plan must survive a handoff.
Either of you should be able to pick it up.
“The money matters, but the money is being asked to serve a life.”Christopher Swan, CFP® · Retire Blessed manuscript
The plan is yours.
The standalone Blueprint includes written advice and a delivery walkthrough. You carry out the plan with your providers. Keep the current copy where both of you can find it.
Further help is a choice.
Further advice, coordination, investment management, or monitoring requires a separate engagement. Tax preparation and legal work remain with your professionals.