Your retirement decisions, organized into a plan you can use.

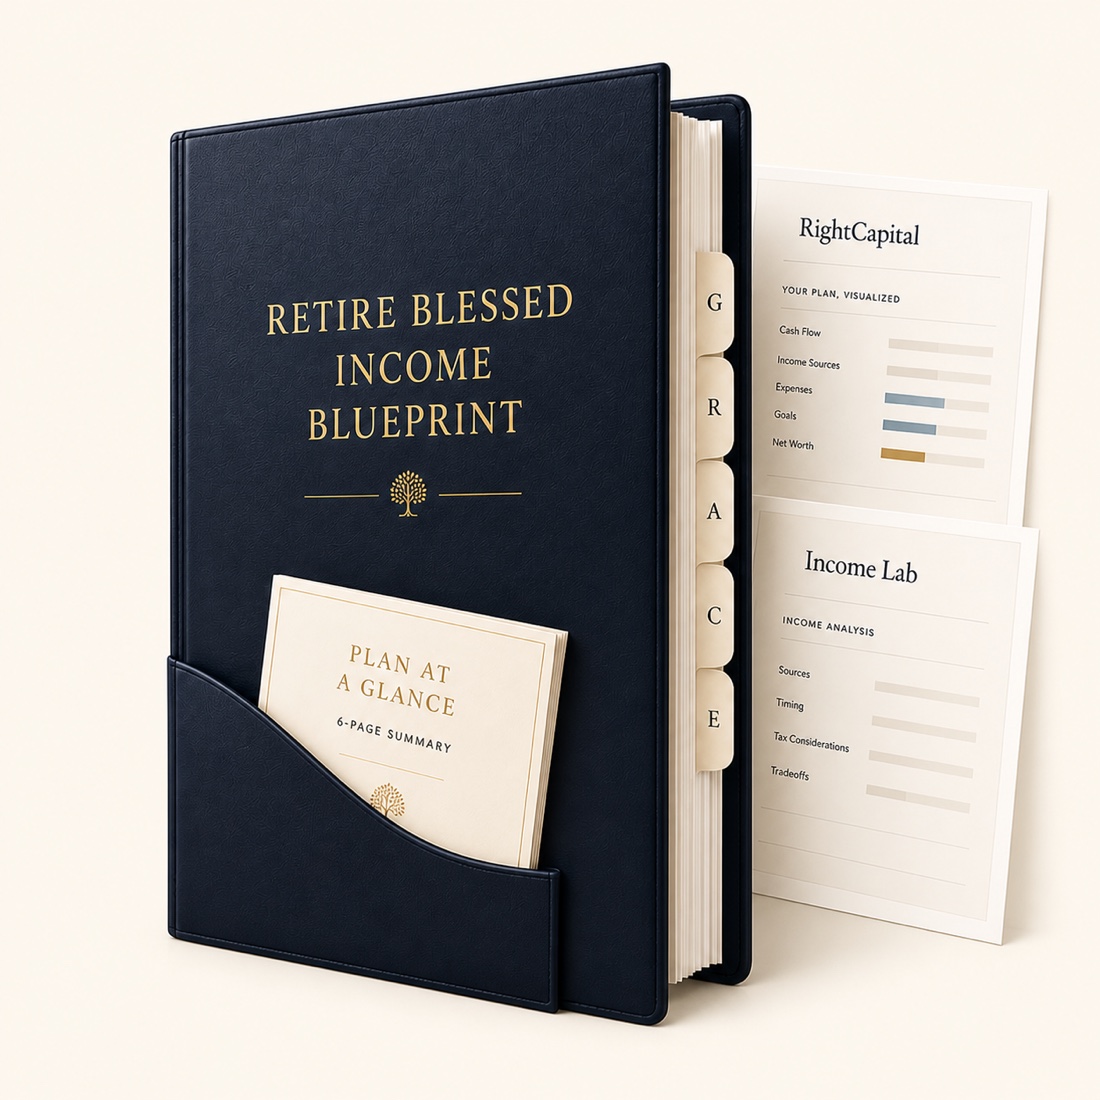
Illustrated Retire Blessed Income Blueprint binder with a six-page summary and supporting RightCapital and Income Lab reports.

A personalized household Blueprint, a short summary for everyday decisions, and supporting planning reports.

Three meetings turn the analysis into a plan you understand and can use.

Most Blueprint engagements follow three working meetings and are completed in about 30 days after I receive the information needed to begin.

  1. Meeting 1

    Build the household picture

    We organize the facts, review the first analysis, and identify the retirement decisions that matter most.

  2. Meeting 2

    Review and refine the plan

    We work through the tradeoffs, correct assumptions, answer questions, and refine the recommendations around your priorities.

  3. Meeting 3

    Receive the Blueprint

    We walk through the finished plan, concise summary, supporting reports, and sequenced action path so you know what comes next.

A detailed Blueprint, a concise summary, and the analysis behind both.

The work is organized for two kinds of reading: a quick return to the decisions that matter now and a deeper reference when you need the reasoning, rules, or next step.

  • Household Blueprint

    A durable binder and matching PDF with your planning rules, recommendations, reasoning, actions, and review triggers.

  • Plan at a Glance

    A concise summary of the decisions and next actions you are most likely to revisit.

  • Action path and evidence

    A sequenced 12-month plan, supported where useful by RightCapital and Income Lab reports.

Retire With Swan Retire Blessed Income Blueprint Illustrative format · Not client data
01 / Retirement Paycheck Map

What may fund life each month

Guaranteed incomeEssential spending Portfolio withdrawalsFlexible spending Cash reservesDisruptions and near-term needs

The written plan can coordinate Social Security, pensions, work income, portfolio distributions, timing, spending needs, and potential gaps.

02 / G.R.A.C.E. Coordination

One plan, solved in order

GIncome RReserves AAssets CTaxes ELegacy

Income, reserves and insurance, asset growth, tax planning, and estate and legacy priorities are considered together rather than as separate assignments.

03 / Decision Register

The reasoning stays attached to the action

Income timingAlternatives, assumptions, and tradeoffsHousehold decision
Withdrawal orderTax and cash-flow coordinationImplementation
Reserve and risk rulesTargets, triggers, and open questionsReview
04 / Implementation Roadmap

Recommendations become owned work

SequencePut actions in decision order.
OwnershipName the household member or professional responsible.
TimingDocument target dates and dependencies.
05 / Review Triggers

Know what should reopen the plan

LifeMarketsTaxesHealthFamilyGoals

The plan can identify the changes that should prompt a new decision instead of relying on the calendar alone.

Illustrative sample pages. The finished Blueprint is personalized to the household and may use a different structure.

You bring the household picture. I organize the work.

Plan for three meetings over about a month, along with document gathering and brief follow-up questions between meetings.

  • Gather what you have

    Income and benefits, spending, accounts, tax returns, insurance, estate documents, and any decision deadlines.

  • Bring the decision-makers

    When a retirement decision affects a spouse or partner, both people participate in the key conversations.

  • Review and respond

    You react to the tradeoffs, answer follow-up questions, and confirm the priorities and assumptions that shape the final plan.

One stated fee for the complete Blueprint.

Stated flat fee for the household Blueprint

The fee is billed in two stages: after the agreement is signed and when the Blueprint is delivered.

The fee covers the planning work, meetings, and written or electronic Blueprint. The engagement ends at delivery and does not renew automatically.

See the current fee and billing details

Use the plan yourself—or choose help putting it to work.

The Blueprint ends when the finished plan is delivered. What happens next is your choice.

Use it yourself

Follow the Blueprint and its action sequence at your own pace.

The 90-Day Bridge

Get implementation-focused, advice-only help for the next 90 days while you keep control of your accounts.

Learn about the Bridge

Ongoing Wealth Management

Continue with ongoing retirement planning and portfolio management for a flat annual fee.

Learn about ongoing help

Blueprint credit: If your first 90-Day Bridge and/or Ongoing Wealth Management engagement begins within 180 days of Blueprint delivery, an eligible portion of the Blueprint fee may be applied as one aggregate credit. See the current amount and full terms.

Start with a Swan Fit Call.

A 20-minute conversation with Christopher about what is changing and whether the Blueprint is the right kind of help.

Start the fit check See the Planning Approach behind the Blueprint